Weekly Manhattan and Brooklyn Market Update: 10/12
Howard Hanna NYC October 12, 2026
Howard Hanna NYC October 12, 2026
The rebound that started last week carried through. Manhattan signed 195 contracts, its busiest week since late July, and Brooklyn signed 122, its most since early August and now ahead of last year’s pace. Meanwhile the fall restock is leveling off: Manhattan inventory rose just 1.2%, the smallest gain of its five-week run, Brooklyn’s supply dipped for the first time in five weeks, and Manhattan’s pending pipeline turned up for the first time in seven weeks.
The Howard Hanna NYC Consumer Sentiment Index increased from +18% to +25%, a second straight gain that puts it well above its pre-pandemic average. What stands out is the backdrop: buyers stepped up their activity in the same week mortgage rates climbed to 7.57%, the highest of the past year.
What This Means for Fall 2026
For buyers: The September window is closing. Manhattan new listings are now running 12% below last year, contract activity is at a two-and-a-half-month high, and the rebuild in pending sales has begun. Selection is still the widest since July, but with financing costs rising and the Fed expected to tighten, waiting is getting more expensive on two fronts: competition for the best homes, and the rate on the loan to buy them.
For sellers: Demand is back in both boroughs, and the flow of new competition has slowed. That is a constructive setup for homes already on the market, provided they are priced realistically. With rates above 7.5%, buyers are acutely payment-sensitive, so the gap between well-priced listings that trade and aspirational ones that sit is likely to widen through the rest of the fall.
Overall, two consecutive weeks of rising contracts, a pending pipeline that has stopped shrinking, and new supply cooling off point to a market that is absorbing its fall restock rather than drowning in it. The open question is rates: if mortgage costs keep climbing toward 8%, this momentum will be tested. For now, demand is holding up better than the financing backdrop would suggest.
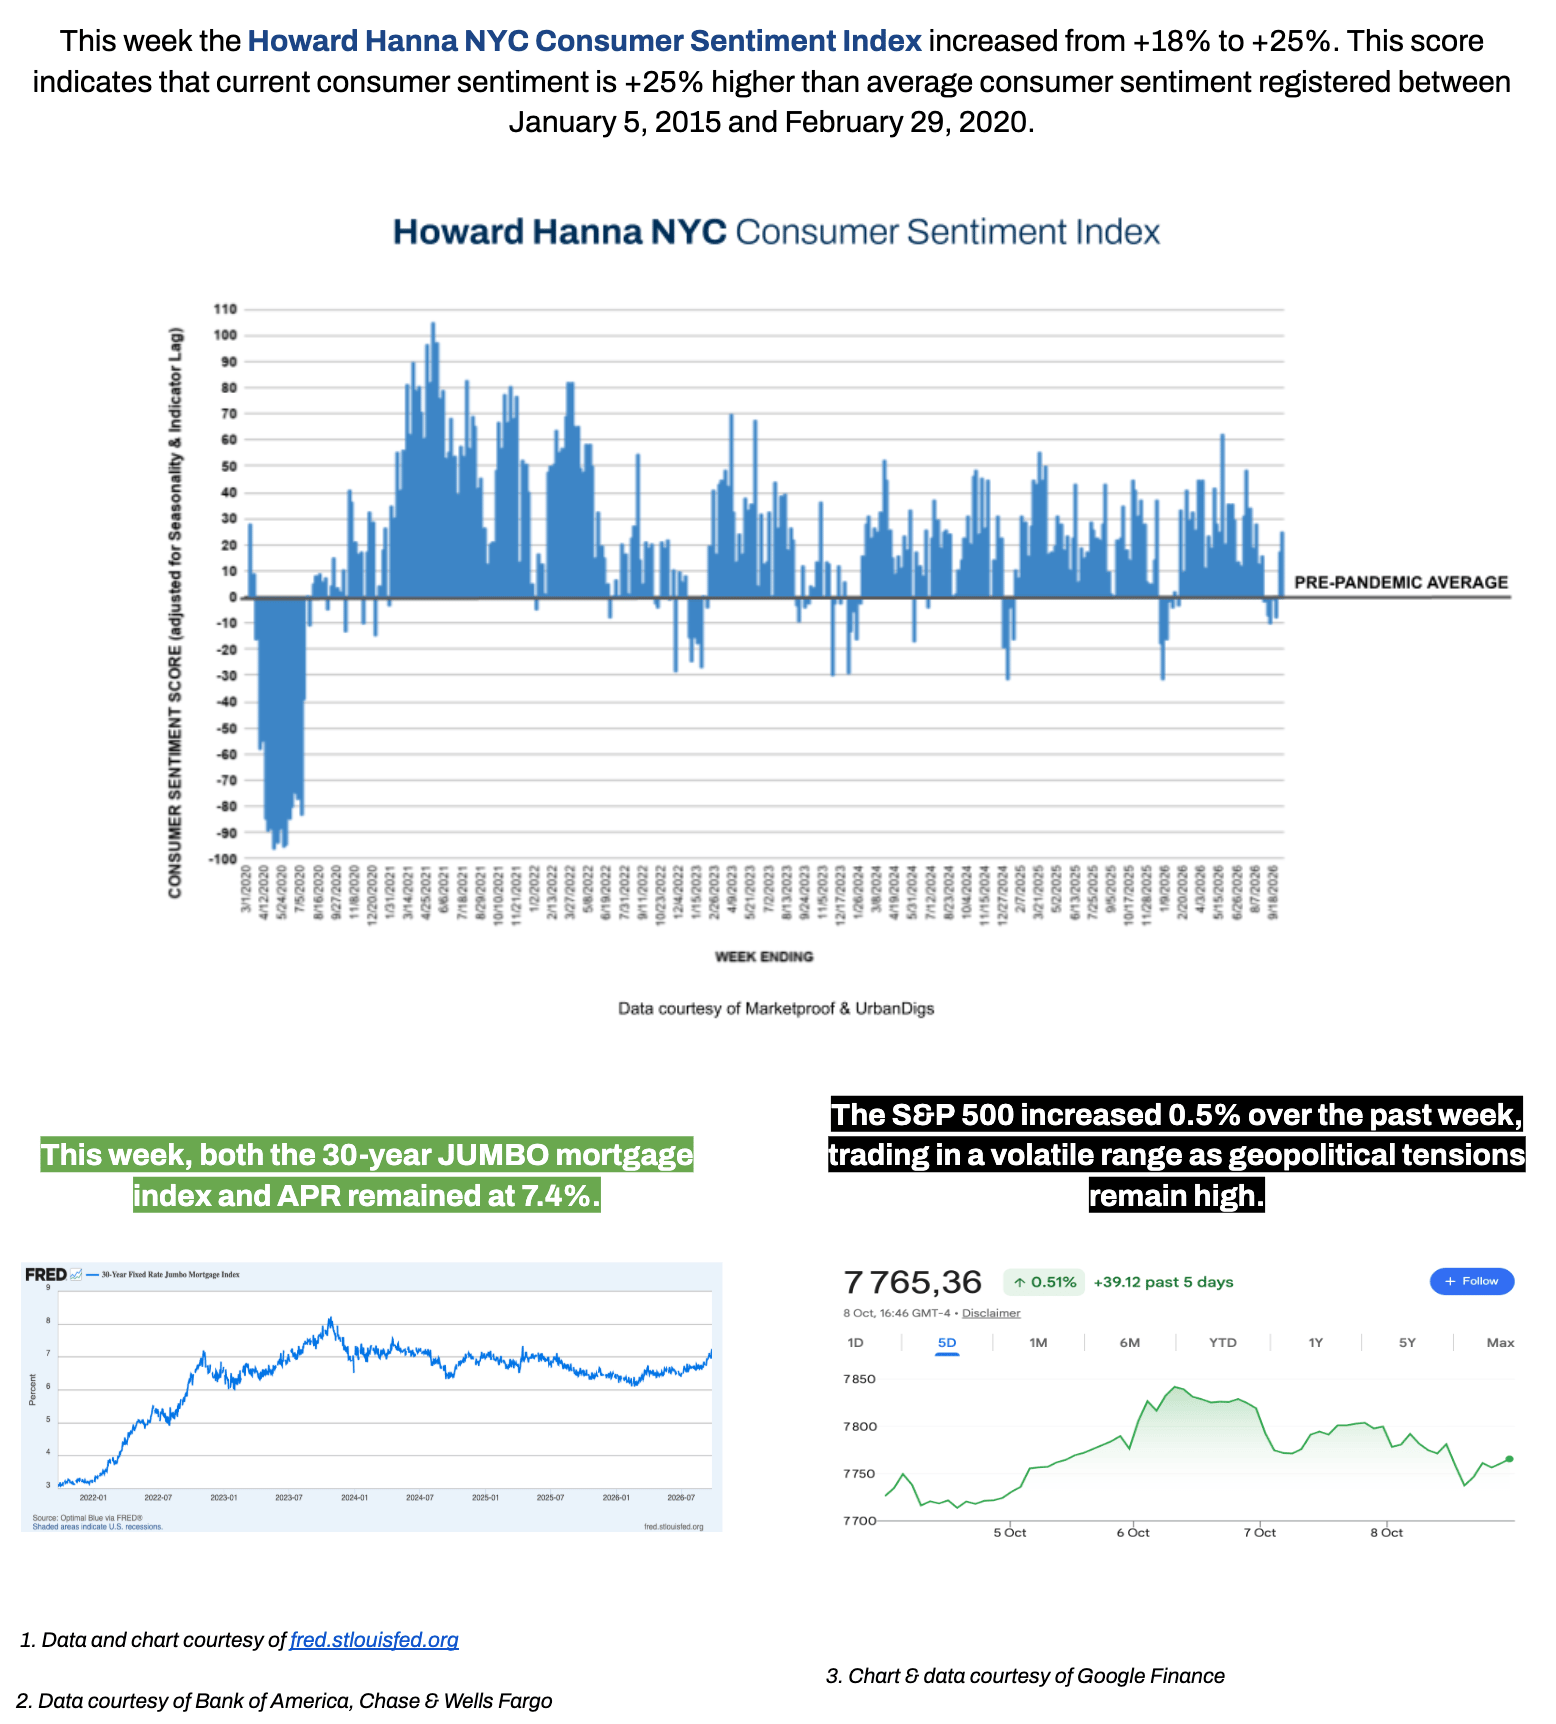
Photo by Rihards Gederts | Howard Hanna NYC
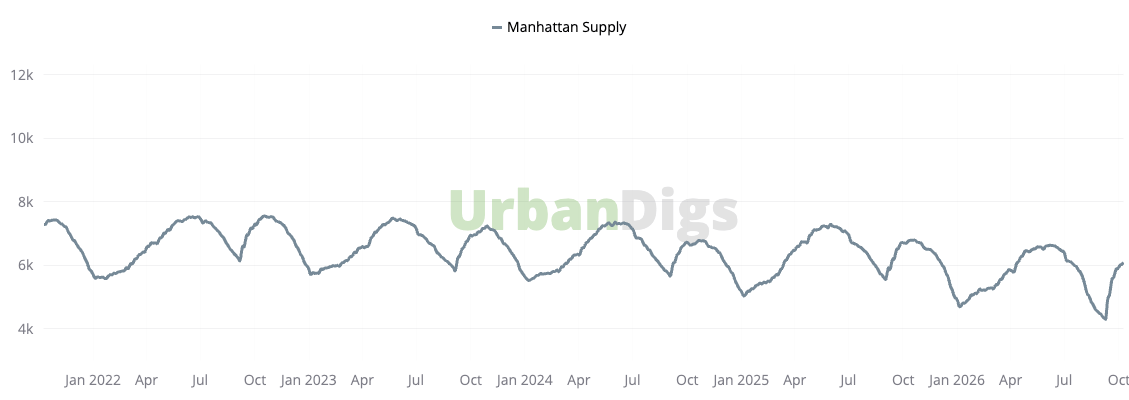
Manhattan active inventory rose to 6,101 homes (+1.2% week-over-week | −9.7% year-over-year), a fifth consecutive weekly increase and the highest count since mid-July. New listings totaled 342 units (−14% week-over-week | −12% year-over-year), the lowest weekly figure since the start of September and the first week this fall to run below last year’s pace.
The restock is losing steam: weekly inventory growth has slowed from +13% in mid-September to +1.2% now. With contracts rising and new listings slowing, Manhattan’s supply is likely close to its fall peak, and the year-over-year deficit, now under 10%, may begin to widen again as the season moves into November.
Brooklyn inventory eased to 3,738 homes (−1% week-over-week | +3.9% year-over-year), the first weekly decline after four straight gains, while remaining above last year’s level. New listings totaled 200 units (+18% week-over-week | +4% year-over-year), a rebound from last week’s low.
Even with fresh supply picking up, inventory fell: more homes left the market than arrived, helped by the borough’s busiest contract week since early August. That is a sign of healthy demand in a borough that still offers more choice than a year ago.
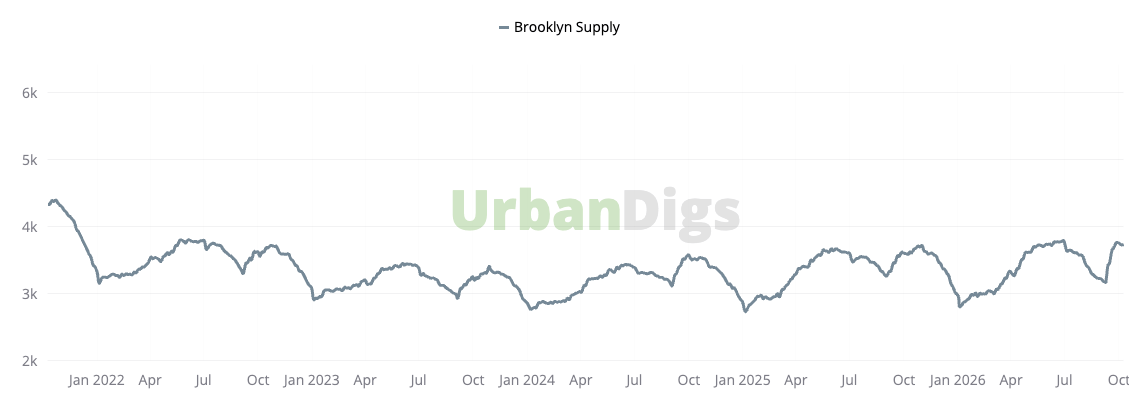
The fall rebuild has started in Manhattan. After six straight weekly declines, pending sales rose as the past two weeks of stronger contract activity began to post. Brooklyn slipped slightly after last week’s uptick, holding near its seasonal floor.
• Manhattan pending sales: up +1.3% week-over-week to 2,869 units, ending a six-week decline.
• Brooklyn pending sales: down −0.6% week-over-week to 1,830 units, essentially flat and at its lowest level since early May.
Manhattan recorded 195 signed contracts (+7% week-over-week | −7% year-over-year), the most since late July and a second consecutive weekly increase, with the gap to last year narrowing from 16% to 7%.
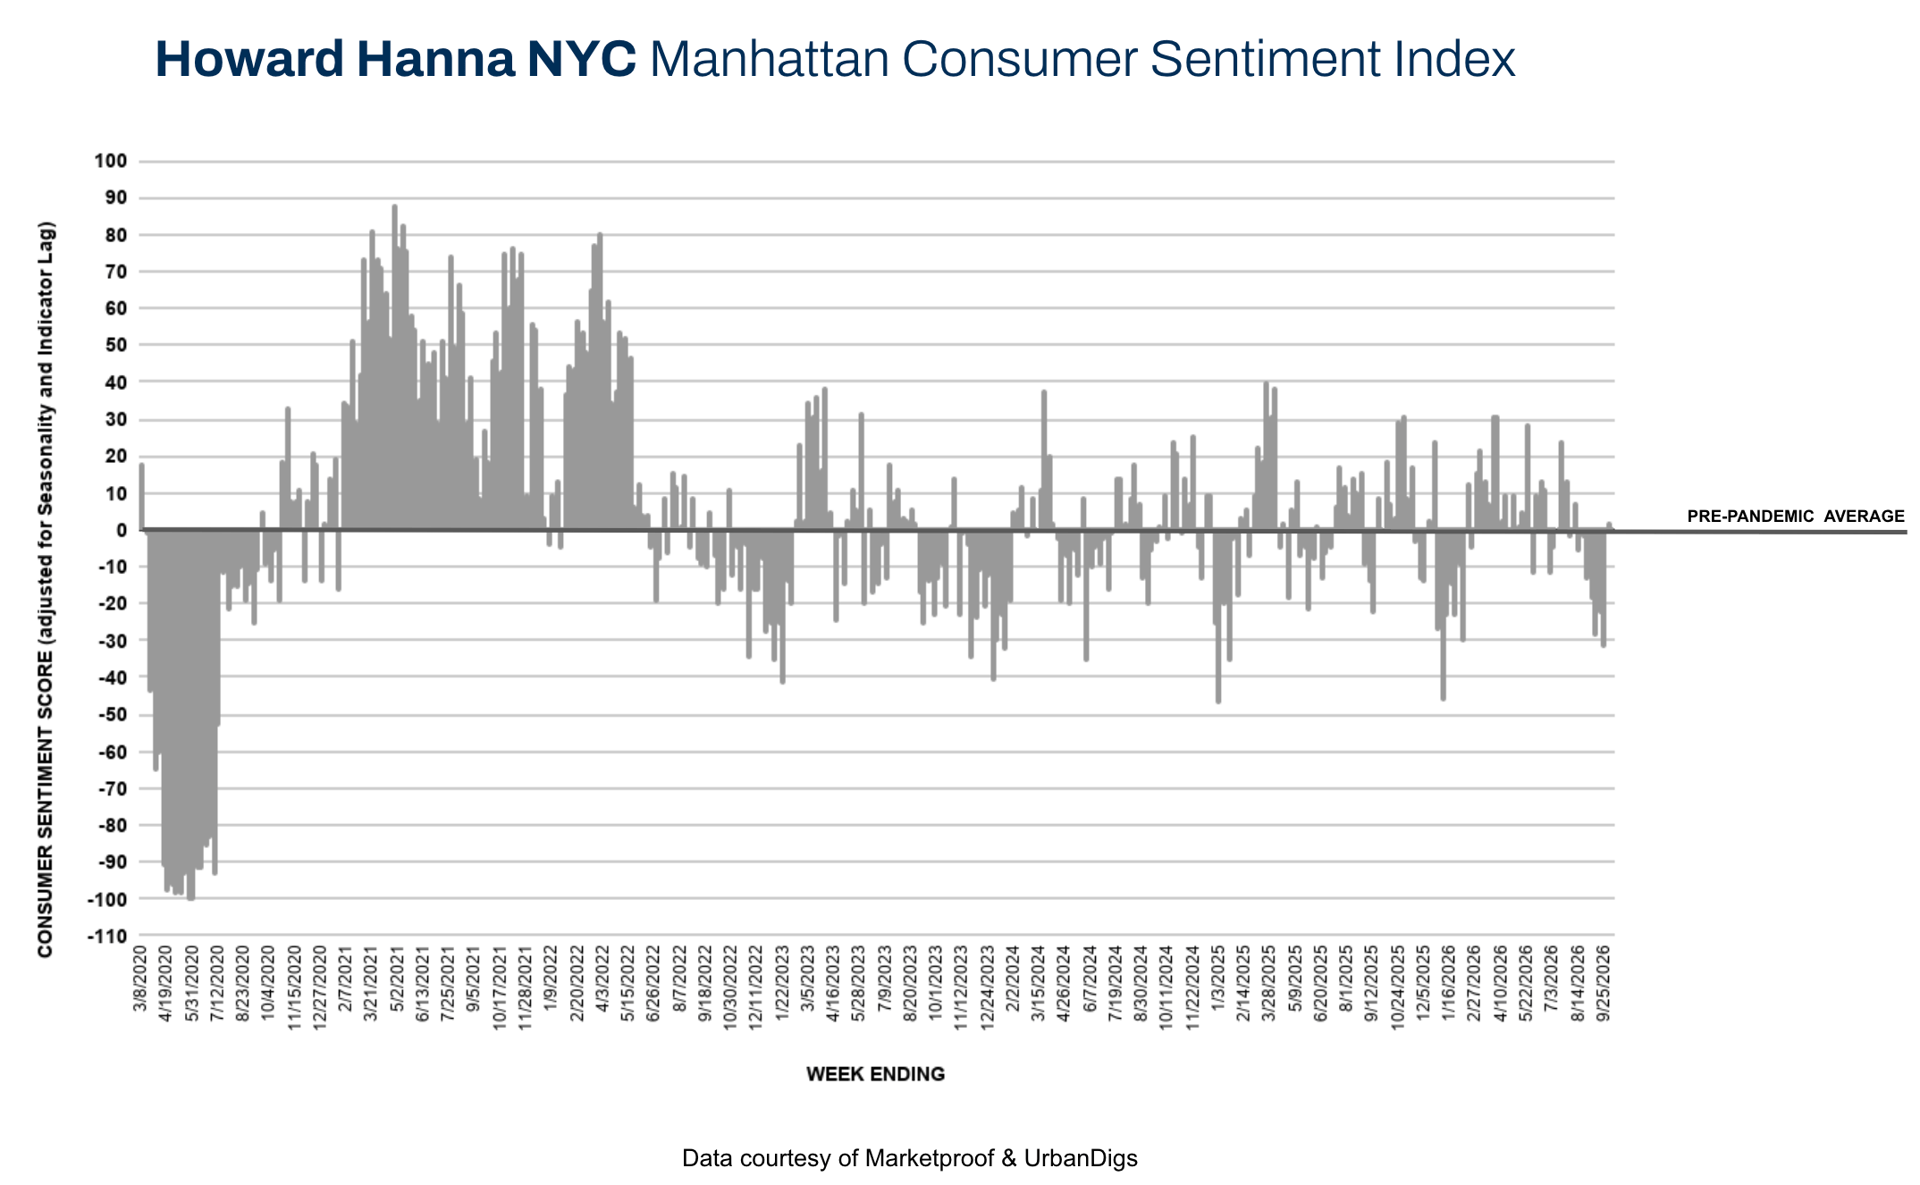
The Howard Hanna NYC Manhattan Consumer Sentiment Index decreased from +2% to +1%, essentially unchanged at its pre-pandemic average. Rising contracts are being balanced by the highest inventory since July, which keeps the gauge at neutral; continued gains in contract activity as supply levels off would push it into positive territory.
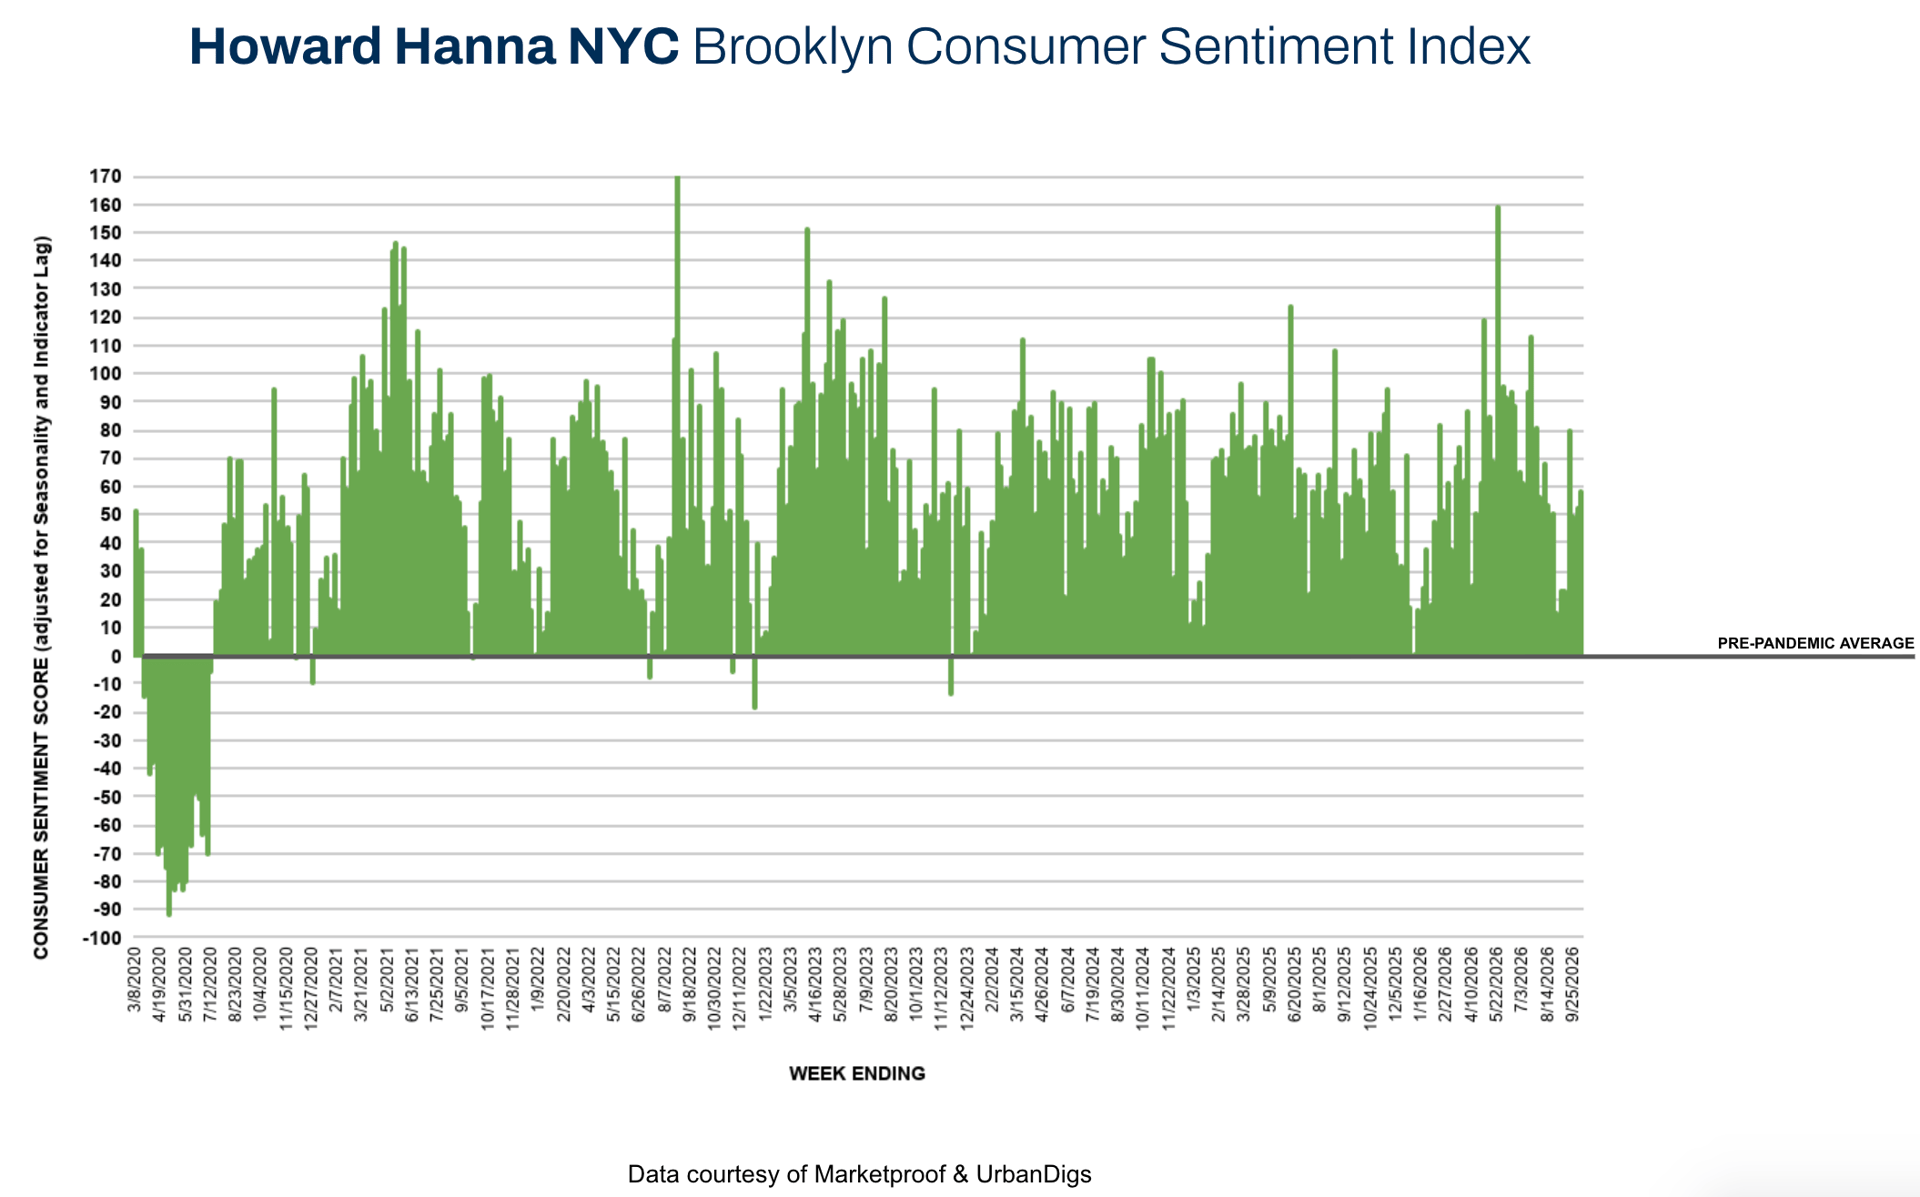
Brooklyn recorded 122 signed contracts (+11% week-over-week | +2% year-over-year), its strongest week since early August and the first week this fall to run ahead of last year.
The Howard Hanna NYC Brooklyn Consumer Sentiment Index increased from +52% to +58%, extending its lead as the stronger of the two boroughs. Rising contracts and a slightly smaller shelf are exactly the combination that lifts this gauge.
According to Marketproof data, new development activity recorded 28 signed contracts across 21 buildings during the week of October 5, 2026. Top-performing developments included:
• Eastlight (Kips Bay) with five signed contracts
• The Emmet Building (NoMad) with three signed contracts
Eastlight returns to the top of the board, and the Emmet Building makes the leaderboard for a third consecutive week, bringing its three-week total to 13 contracts. Sustained demand at well-positioned projects is consistent with the Q3 data above: new development inventory is at its lowest level since 2014, so the buildings buyers want are selling steadily.
Howard Hanna NYC brings the nation’s largest independent and family-owned brokerage to New York City, uniting the strength of a national network with the insight and sophistication of a local firm. Formed through joining forces with Elegran Real Estate, Howard Hanna NYC delivers a seamless, full-service experience backed by more than 15,000 agents across 500 offices in 14 states. The firm’s forward-thinking, agent-first culture continues to shape the future of real estate across Manhattan and the Tri-State area. Learn more at www.howardhannanyc.com.
Her experience, expertise, and engaging personality make Sonal the perfect combination of advisor, advocate, and strategist. She is the proud owner of several NYC properties and a skilled negotiator with a deep understanding of people and sharp instincts about market trends.